Last week, I shared the first part of my 'adventure' with G.K. (G.K. is for Gate Keeper, a junior officer I encountered during a recent 401(k) review for a local business.) There is certainly a lot of danger in sponsoring a 401(k) plan for your employees when you don't give a s*** about it.
Danger to employees - They aren't getting the most from this company benefit - which affects their future
and their abilty to retire later.
Danger to employer - By not taking their fiduciary responsibiltity seriously, the company may be open
to potential legal action.
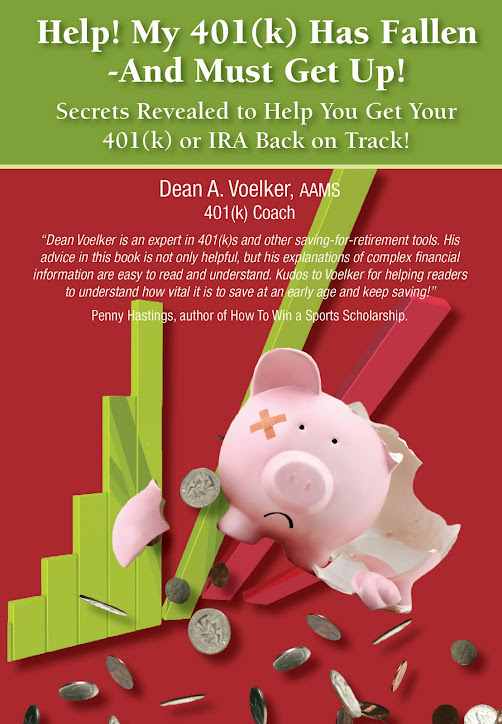
The problem is that there are too many "wimpy" G.K.s out there. I am purposely leaving the name generic, so you may ask yourself "Is this MY company?" People like G.K. are one of the main reasons I wrote the book, "Help! My 401(k) Has Fallen - And Must Get Up!" You need to know what to do if you are stuck in a bad 401(k) plan. You also need to know what to do if your employer is "wimpy".
Anyway, as I mentioned in my post last week, I had asked G.K. my usual review questions and was suprised at her careless attitude towards their plan. She had provided me with a 2008 version of their enrollment kit. This was for me to prepare a report on their mutual funds in terms of performance and expenses.
After seeing this, I was pretty sure what to expect. I knew that I could help this company, but only if I was able to talk to the right people. I asked G.K. to please have the President and Vice President available for our next meeting. She said she would 'try' to do this. I told her how urgent this was. The others MUST be present. At the very least, have ONE of them. She needed to understand that being negligent about the plan was costing them money. Surely the other guys would get that.
We scheduled a follow-up appointment on a time when the Pres. & V.P. were scheduled to be in the office.
How did the funds look? Hmmm......imagine letting your lawn grow for several months without mowing or watering. That should give you a pretty good idea.
There were 59 funds in all! That is already a problem, even if they were all great. Imagine going to a restaurant and being handed a menu with that many entree choices (which happens). What do you do?
How long does it take to decide? If it is that hard in a restaurant, imagine poring over mutual funds.
People want SIMPLE! A good selection for a 401(k) is 15-20 funds which include the best possible ones in each asset class.
One of my resources allows me to measure funds and compare them to their peer group. A Large Company fund is compared to other Large Company funds. Internationals are compared to other internationals. In other words - apples to apples. Funds are measured in terms of performance, management fees, risk, and Morningstar ratings.
The finished report tells us very simply whether the fund passes or fails. Passing funds are printed in GREEN on the report. Failing funds are printed in RED. How is that for SIMPLE?
Guess what? Would you believe that 51 out of 59 funds were in RED?
Well, I burned up my toner cartridge and printed out 3 copies of this "tree-killer" report. That showed the problem clearly enough. Now I needed a solution for the company. We needed to address the glaring issues of monitoring mutual funds regularly and keeping fees low. As an advisor, I would also need to be pro-active in showing employees how to use the plan. As long as the "powers that be" were there, I felt pretty good about being able to serve them.
Another great benefit for the company was that because the plan held more than $1 Million in assets, there is no cost for them to change!
Ask Yourself This: If you could trade in your broken down, smelly, rusted out 1980's gas guzzler for a shiny new car - and the cost to you was ZERO - how long would it take to decide?
Wouldn't you know it though? Even though I had called G.K. the day before to confirm that everyone would be there......when I showed up, they were missing. No President. No Vice President. Only G.K.
She mumbled an "apology" without looking me in the eye, saying that "something had suddenly come up" for the guys and I could just show her my report.
"Something suddenly came up"? What is this - a 'Brady Bunch' episode?
I showed her my report and pointed out my concerns. When I showed her the mutual funds and that 51 out of 59 were in RED, she started looking for which funds were most common to the plan. Then she looked up HER OWN PLAN to see if HER funds were Green or Red. For a few seconds, I could only stare in disbelief - What kind of MORON is this??
I interrupted the insanity. "Ummm....Aren't we missing the big picture here? Rather than try to pick out individual funds, wouldn't you be concerned that 51 out of 59 are failing? You have a real need for a system to monitor the funds in your plan on a regular basis - which lowers your company liability. Think of it this way - if you have a bunch of bananas in the house, and they've gone brown and soft, what would you do? Would you try to pick out a few good parts? Or would it really be better to replace the bananas?"
G.K. thought for a bit, and admitted that I may have a point.
Amazing! Was I actually getting through?
Not really. G.K. sat there as I pointed out a few other red flags, then said goodbye. "I'll share this with the others. We'll call you if we're interested."
Let me make this clear. I'm not mocking G.K. and the company because they have a bad 401(k) plan. Also, I know not everyone will work with me as their 401(k) advisor. However, the reason for my anger is that the plan stinks - AND they aren't willing to do anything about it!
Again - If you could trade in your broken down, smelly, rusted out 1980's gas guzzler for a shiny new car - and the cost to you was ZERO - how long would it take to decide?
There are too many G.K.s out there - Lazy, narrow-minded people who oversee the 401(k) at your company. That's why I wrote this book, "Help! My 401(k) Has Fallen - And Must Get Up!" due out soon. This is to help YOU fight back - AND get more from your 401(k).
You can contact me at http://www.helpmy401k.us/. I am also at Linked In. You can pick up your free report on my website – "The 5 Biggest Problems With 401(k) Plans – And How to Fix Them".
My weekly financial advice program, Improving Your Financial Health is on Blog Talk Radio and Saturday mornings at WHME-FM.
Showing posts with label fiduciary. Show all posts
Showing posts with label fiduciary. Show all posts
Wednesday, March 31, 2010


Friday, March 26, 2010
Is Your Employer 'Wimpy'?

When was the last time you had something happen that really pissed you off - but you were also extremely thankful for it?
First, if you are offended by the word "pissed", I apologize. I use that word to get your attention and it does a much better job of describing my feelings in this case than "angry" or "mad". I was "pissed" because I witnessed some real wimpiness from an employer.
I did a 401(k) plan review for a local small business recently. These reviews are to help employers to look at their retirement savings plans and find places where they can improve. The goal for everyone is to lower their fees, reduce their liability, and provide better education for employees as well. Everyone wins!
So what pissed me off? My contact person at the company ABSOLUTELY DID NOT CARE!! It doesn't bother me if someone doesn't know their 401(k), and wants to learn. It bothers me greatly when you don't give a ****. She wasn't even the owner, but a rather small-minded, pencil-pushing "Gate Keeper".
Why am I extremely thankful? Simple. This is one of the main reasons I wrote my book "Help! My 401(k) Has Fallen - And Must Get Up!"
There are some wimpy employers out there, and this "Gate Keeper" (I'll refer to her as G.K.) was a vivid example of what's wrong with many 401(k) plans today. She is part of a 3 person 401(k) committee, which also included the company president and V.P. The first part of my review is a questionaire and gathering information about the funds in the plan.
Money Magazine Senior Writer Penelope Wang wrote a recent article "Make the Best of a Bad 401(k)" . She points out that "even the nation's biggest 401(k) plans fall short in some key areas".
Employers must understand that they have a fiduciary responsibility to their employees. If a retirement plan is offered by the company, it needs to include the best possible mutual funds at the lowest possible cost. Also, employees must be kept well-informed about how the plan works and what the benefits are.
Fiduciary responsibility is not just a "good idea". Its the law, part of the Pension Protection Act of 2006, and recent updates to ERISA (Employee Retirement Income Security Act). Companies may be exposed to potential lawsuits by not doing their best for their employees.
Let's get back to "G.K." Here are some of the highlights (or lowlights) of her responses to my questions about their plan.
Q: How often does the trustee committee meet to review the plan.
A: We let the advisor take care of that.
Q: Are all 3 members of your committee aware of the meaning & responsibility of being a 'fiduciary'?
A: Yes.
Q: Are you also aware of potential personal liability which comes with fiduciary repsonsibility?
A: Well, that's what we have insurance for.
Q: How does your company help the participants in the plan to make informed investment decisions?
A: Information is available on-line and they can call the advisor.
Q: How often does he meet with your employees?
A: I think once a year. People can call him if they have other questions.
Q: What process do you use for monitoring the mutual funds in the plan for performance and expenses?
A: We rely on the advisor for that.
Q: Do you have a current enrollment kit?
A: (She handed me a packet from 2008 - NO KIDDING, I couldn't make this stuff up!)
Q: Do you have a more current kit?
A: Our advisor needs to get us some new ones. We haven't had any new employees so it hasn't been
needed.
Q: How are employees kept informed of mutual fund expenses?
A: We rely on the advisor for that.
There is more, but you get the idea. People like G.K. just don't get it. Her small-minded attitude costs her company money. She is also depriving the employees there of their rights to learn more about their benefits and their rights to better investments. (I will talk about this in the next segment. Stay tuned - it gets MUCH WORSE when we review the investments.)
The bad news is that there are plenty of G.K. s out there. If I were an employee at this company, I'd either want a different person in charge of the 401(k) plan or learn what my legal options are. G.K. is a time-bomb.
You can contact me at http://www.helpmy401k.us/ . Pick up your free report on my website – "The 5 Biggest Problems With 401(k) Plans – And How to Fix Them". My new book, "Help! My 401(k) Has Fallen - And Must Get Up!" is due out in April.
My weekly financial advice program, Improving Your Financial Health is on Blog Talk Radio and Saturday mornings at WHME-FM.
Subscribe to:
Posts (Atom)