One of the things I wasn't looking forward to with my book was typesetting. I am actually not the greatest typist in the world, and Microsoft Word isn't equipped for a clean copy. Typesetting means 'formatting' the words so that all paragraphs and spacing is even, and all graphs look clean and sharp.
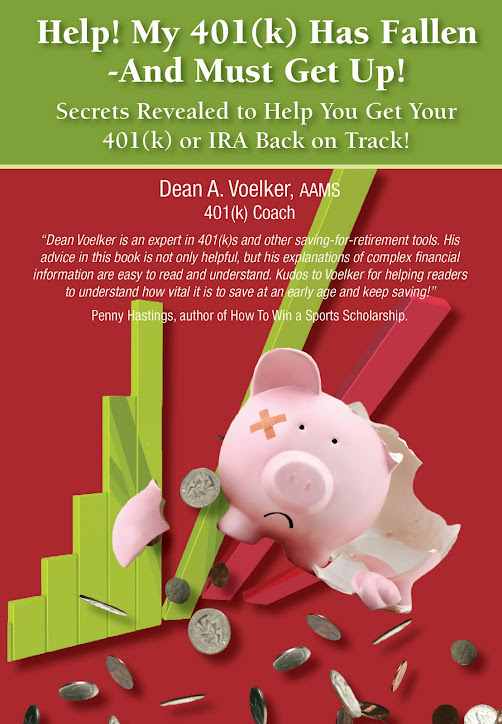
When you self-publish, typesetting is one of those things that will make the book look more professional as opposed to just having it printed yourself. "Help! My 401(k) Has Fallen - And Must Get Up!" may sound like a catchy title, but I really want a professional look for it, not a 'wimpy' one. This is an opportunity to establish myself as THE authority on 401(k) plans.
I had about 2 options for this. First, I could have used Create Space, which will also assemble and print the book. Since Create Space is part of Amazon, they will also handle the customer ordering and shipping. They offered to do the typesetting also, and thought they could do it for about $1000 for my 100 page book.
They also told me that because I am using some graphs and tables in the book, I should make the size about 7"x10". Fine with me. I just need to let my graphic artist, Aimee Sims know that.
From reading "The Well-Fed Self Publisher" by Peter Bowerman, he also makes suggestions for firms which he uses to get his books done. Peter seems like a straight shooter, who knows what he is talking about, so I e-mailed a copy to a firm he endorses, Hoehne-Werner Book & Graphic Design.
I have spoken with Angela Werner there, and looked at their work on the website. Angela gave me an estimate of $800. If they are good enough for Peter, they are good enough for me. He suggests cutting costs where possible. Its also important to remember that you get what you pay for. With Hoehne-Werner, I believe it will be the right call. Typesetting is their specialty.
One thing I learned right away - I had wasted a LOT of time putting page numbers with my index. Angela suggested taking the page numbers out. Once the book is typeset, the page numbers could easily change!
"D'OH!" Oh well, I will know that next time.
The whole process should take about a month, so I am hoping to have the book out now by the end of May.
You can contact me for more information on "Help! My 401(k) Has Fallen - And Must Get Up!" at my website, http://www.helpmy401k.us/. Follow me on Linked In or Twitter also. I am currently hosting an advice show, "Improving Your Financial Health" on Blog Talk Radio, which also airs on Harvest 103.1 WHME-FM in South Bend.
Showing posts with label wimpy. Show all posts
Showing posts with label wimpy. Show all posts
Wednesday, April 7, 2010


Friday, March 19, 2010
Diary of a Wimpy 401(k) - Wimpy Cost Explanation
When I go to buy something – a new pair of shoes, furniture, or dinner at a restaurant – I want to know exactly what I am paying for. You probably do also, unless your name is Bill Gates. Fee clarity is more important than ever.
Since I have been an advisor in South Bend, I’ve gotten to know a lot of people. I’ve been asked on several occasions to join marketing or networking groups. Recently I was invited to join a group which focused on marketing ideas. The ideas seemed good, and I saw some value in joining the group. I thought it may be a great way to plug the upcoming book as well.
However, this week I decided absolutely not to join this marketing group.
Why not ? The group leader did a poor job of explaining all of the costs involved (wimpy?). I went to 3 different meetings, I was bombarded with marketing information, but never once saw cost explained either verbally or in print. When I finally did find out HOW MUCH, it was quite a lot more than what I was originally told. Whatever credibility he had worked to build was gone.
“No B.S.”?…….Yeah, Riiiiiiiiight. One of my first sales managers told me “A confused prospect never buys.”
What does this have to do with 401(k) plans? Simple. One of the biggest problems with plans now is that fees aren’t clearly explained. Employers don’t know costs, and therefore can’t explain them to employees, who are really picking up the bill. Federal law has made it mandatory that all fees for 401(k) plans are clearly itemized and easy to understand.
If a contractor came to my house and told me he would fix my roof for $10,000, and then due to “unforseen expenses” the tab came to $15,000 or more, I’d be upset. You would be too! By the same token, when I review plans for employers, I want to make sure they know all of the fees in the plan. I have also stumbled onto plans which are badly in need of an update. They are still paying for the plan as a ’small’ business, when in fact they could be saving a lot of money once they have reached certain dollar amounts, or breakpoints.
In my book, “Help! My 401(k) Has Fallen – And Must Get Up!” I use an example of cell phones to explain this.
Why would you still pay for a “1980’s backpack style” cell phone, when newer, better, and cheaper models are available?
As an employer, you need to review your 401(k) plan and update it. Don’t be ‘wimpy’. Make sure you know all the costs and your people do too.
You can also get a copy of a free report on my website – “The 5 Biggest Problems With 401(k) Plans – And How to Fix Them”.
You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.
Since I have been an advisor in South Bend, I’ve gotten to know a lot of people. I’ve been asked on several occasions to join marketing or networking groups. Recently I was invited to join a group which focused on marketing ideas. The ideas seemed good, and I saw some value in joining the group. I thought it may be a great way to plug the upcoming book as well.
However, this week I decided absolutely not to join this marketing group.
Why not ? The group leader did a poor job of explaining all of the costs involved (wimpy?). I went to 3 different meetings, I was bombarded with marketing information, but never once saw cost explained either verbally or in print. When I finally did find out HOW MUCH, it was quite a lot more than what I was originally told. Whatever credibility he had worked to build was gone.
“No B.S.”?…….Yeah, Riiiiiiiiight. One of my first sales managers told me “A confused prospect never buys.”
What does this have to do with 401(k) plans? Simple. One of the biggest problems with plans now is that fees aren’t clearly explained. Employers don’t know costs, and therefore can’t explain them to employees, who are really picking up the bill. Federal law has made it mandatory that all fees for 401(k) plans are clearly itemized and easy to understand.
If a contractor came to my house and told me he would fix my roof for $10,000, and then due to “unforseen expenses” the tab came to $15,000 or more, I’d be upset. You would be too! By the same token, when I review plans for employers, I want to make sure they know all of the fees in the plan. I have also stumbled onto plans which are badly in need of an update. They are still paying for the plan as a ’small’ business, when in fact they could be saving a lot of money once they have reached certain dollar amounts, or breakpoints.
In my book, “Help! My 401(k) Has Fallen – And Must Get Up!” I use an example of cell phones to explain this.
Why would you still pay for a “1980’s backpack style” cell phone, when newer, better, and cheaper models are available?
As an employer, you need to review your 401(k) plan and update it. Don’t be ‘wimpy’. Make sure you know all the costs and your people do too.
You can also get a copy of a free report on my website – “The 5 Biggest Problems With 401(k) Plans – And How to Fix Them”.
You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.
Wednesday, March 17, 2010
Diary of a Wimpy 401(k) - Wimpy Friends
The interesting thing about writing a book - I am learning who my friends are.
One of the things I had wanted was to get testimonials from people from all walks of life. The book was written in simple language with plenty of stories to make it easy for anyone to understand.
We all have a 401(k) or 403(b) - almost all of us anyway. Unless you are self-employed or one of the rare few who still have a pension.
So about a month ago, I sent requests for testimonials to about 65 people. Some I knew better than others. Some were financial experts who I had interviewed on "Improving Your Financial Health". Some were friends in the financial industry. Some were friends and clients I knew locally, or small business owners. Still others were people who were involved in the project in some way.
A few were celebs who I didn't know, but I wanted to get a testimonial from them.
In asking for testimonials, I believe that we are all very busy. I am willing to be patient and follow up a few times to get testimonials. These 'blurbs' from others can help to promote the book.
If you have a 401(k) and you aren't happy with it, and you are nervous about the future, you should read this book!
One guy (a writer whom I won't name) turned me down, but was very nice about it. He explained that he gets many similar requests and he simply does not have time to answer them all. He also didn't believe that his testimonial would carry much weight, with him not having a financial background.
Although I was slightly disappointed, I appreciated his sincerity and his prompt response.
I've also had a few of my financial heroes tell me that although they like the book and see its value, they aren't allowed to respond due to compliance constraints. Again, I respect this.
That's one way to do it. Here's the WRONG WAY!
Another previous guest on my program (I won't name her - but I promise she WON'T BE BACK!) had her assistant send this "snooty form letter" remark. "As a policy, our team focuses on content that is being published by a major imprint. We don’t read or consider unsolicited material. Should your book get picked up by a major imprint, please do feel free to reach out to me at that time, and I’ll do my best to get it to (her) for a possible endorsement."
Again, this type of chilly response really alienated me. I've lost a lot of respect for this person and needless to say, she won't be back as a guest on my program.
I am still looking for testimonials. I've gotten several very ones so far. Let me kinow if you'd like a copy of the book for review. If you want to learn more about 401(k)s and think you can write a couple of kind words - contact me and I will gladly send you a copy of the draft.
Here are some of my favorite testimonials so far.
"Unless you plan to work till you drop, the 401(k) is your eventual ticket to freedom. Your plan may have fallen in 2008 and Dean Voelker is just the person to help get it back up." -
Jonathan Chevreau, Financial Post columnist, and author of Findependence Day.
“Dean Voelker does a great job of laying out the case for aggressively pursuing your 401(k). This book presents compelling reasons for getting involved in your future TODAY, rather than tomorrow. Dean’s story telling approach takes the 401(k) from its birth through today in an easy to read and storytelling manner.” - Len Fox, author of Recipe Investing.
“Dean Voelker is a real pro. He reveals some things about the Social Security system and how
401(k)s work that I never knew. This book is short, sweet and to the point. Everyone needs to read it quickly to see if they are doing what they should to get their retirement plans back on track. Thanks, Dean for putting this together for us.” - John S. Cohoat, President of Cohoat Business Growth Advisors, and author of No Thank You, Mr. President.
Go ahead, don't be "wimpy". Contact me today. You can also get a copy of a free report on my website -
"The 5 Biggest Problems With 401(k) Plans - And How to Fix Them"
You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.
One of the things I had wanted was to get testimonials from people from all walks of life. The book was written in simple language with plenty of stories to make it easy for anyone to understand.
We all have a 401(k) or 403(b) - almost all of us anyway. Unless you are self-employed or one of the rare few who still have a pension.
So about a month ago, I sent requests for testimonials to about 65 people. Some I knew better than others. Some were financial experts who I had interviewed on "Improving Your Financial Health". Some were friends in the financial industry. Some were friends and clients I knew locally, or small business owners. Still others were people who were involved in the project in some way.
A few were celebs who I didn't know, but I wanted to get a testimonial from them.
In asking for testimonials, I believe that we are all very busy. I am willing to be patient and follow up a few times to get testimonials. These 'blurbs' from others can help to promote the book.
If you have a 401(k) and you aren't happy with it, and you are nervous about the future, you should read this book!
One guy (a writer whom I won't name) turned me down, but was very nice about it. He explained that he gets many similar requests and he simply does not have time to answer them all. He also didn't believe that his testimonial would carry much weight, with him not having a financial background.
Although I was slightly disappointed, I appreciated his sincerity and his prompt response.
I've also had a few of my financial heroes tell me that although they like the book and see its value, they aren't allowed to respond due to compliance constraints. Again, I respect this.
That's one way to do it. Here's the WRONG WAY!
Another previous guest on my program (I won't name her - but I promise she WON'T BE BACK!) had her assistant send this "snooty form letter" remark. "As a policy, our team focuses on content that is being published by a major imprint. We don’t read or consider unsolicited material. Should your book get picked up by a major imprint, please do feel free to reach out to me at that time, and I’ll do my best to get it to (her) for a possible endorsement."
Again, this type of chilly response really alienated me. I've lost a lot of respect for this person and needless to say, she won't be back as a guest on my program.
I am still looking for testimonials. I've gotten several very ones so far. Let me kinow if you'd like a copy of the book for review. If you want to learn more about 401(k)s and think you can write a couple of kind words - contact me and I will gladly send you a copy of the draft.
Here are some of my favorite testimonials so far.
"Unless you plan to work till you drop, the 401(k) is your eventual ticket to freedom. Your plan may have fallen in 2008 and Dean Voelker is just the person to help get it back up." -
Jonathan Chevreau, Financial Post columnist, and author of Findependence Day.
“Dean Voelker does a great job of laying out the case for aggressively pursuing your 401(k). This book presents compelling reasons for getting involved in your future TODAY, rather than tomorrow. Dean’s story telling approach takes the 401(k) from its birth through today in an easy to read and storytelling manner.” - Len Fox, author of Recipe Investing.
“Dean Voelker is a real pro. He reveals some things about the Social Security system and how
401(k)s work that I never knew. This book is short, sweet and to the point. Everyone needs to read it quickly to see if they are doing what they should to get their retirement plans back on track. Thanks, Dean for putting this together for us.” - John S. Cohoat, President of Cohoat Business Growth Advisors, and author of No Thank You, Mr. President.
Go ahead, don't be "wimpy". Contact me today. You can also get a copy of a free report on my website -
"The 5 Biggest Problems With 401(k) Plans - And How to Fix Them"
You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.
Subscribe to:
Posts (Atom)