New Book - Coming November 2010

New Book - Coming November 2010
Help! My 401(k) Has Fallen - And Must Get Up!

Friday, March 26, 2010

Is Your Employer 'Wimpy'?


When was the last time you had something happen that really pissed you off - but you were also extremely thankful for it?

First, if you are offended by the word "pissed", I apologize. I use that word to get your attention and it does a much better job of describing my feelings in this case than "angry" or "mad". I was "pissed" because I witnessed some real wimpiness from an employer.

I did a 401(k) plan review for a local small business recently. These reviews are to help employers to look at their retirement savings plans and find places where they can improve. The goal for everyone is to lower their fees, reduce their liability, and provide better education for employees as well. Everyone wins!

So what pissed me off? My contact person at the company ABSOLUTELY DID NOT CARE!! It doesn't bother me if someone doesn't know their 401(k), and wants to learn. It bothers me greatly when you don't give a ****.  She wasn't even the owner, but a rather small-minded, pencil-pushing "Gate Keeper".

Why am I extremely thankful? Simple. This is one of the main reasons I wrote my book "Help! My 401(k) Has Fallen - And Must Get Up!"

There are some wimpy employers out there, and this "Gate Keeper" (I'll refer to her as G.K.) was a vivid example of what's wrong with many 401(k) plans today. She is part of a 3 person 401(k) committee, which also included the company president and V.P. The first part of my review is a questionaire and gathering information about the funds in the plan.

Money Magazine Senior Writer Penelope Wang wrote a recent article "Make the Best of a Bad 401(k)" . She points out that "even the nation's biggest 401(k) plans fall short in some key areas". 

Employers must understand that they have a fiduciary responsibility to their employees. If a retirement plan is offered by the company, it needs to include the best possible mutual funds at the lowest possible cost. Also, employees must be kept well-informed about how the plan works and what the benefits are.

Fiduciary responsibility is not just a "good idea". Its the law, part of the Pension Protection Act of 2006, and recent updates to ERISA (Employee Retirement Income Security Act).  Companies may be exposed to potential lawsuits by not doing their best for their employees.

Let's get back to "G.K." Here are some of the highlights (or lowlights) of her responses to my questions about their plan.

Q: How often does the trustee committee meet to review the plan.
A: We let the advisor take care of that. 

Q: Are all 3 members of your committee aware of the meaning & responsibility of being a 'fiduciary'?
A: Yes. 

Q: Are you also aware of potential personal liability which comes with fiduciary repsonsibility?
A: Well, that's what we have insurance for.

Q: How does your company help the participants in the plan to make informed investment decisions?
A: Information is available on-line and they can call the advisor. 

Q: How often does he meet with your employees?
A: I think once a year. People can call him if they have other questions.

Q: What process do you use for monitoring the mutual funds in the plan for performance and expenses?
A: We rely on the advisor for that.

Q: Do you have a current enrollment kit?
A: (She handed me a packet from 2008 - NO KIDDING, I couldn't make this stuff up!)

Q: Do you have a more current kit?
A: Our advisor needs to get us some new ones. We haven't had any new employees so it hasn't been
     needed.

Q: How are employees kept informed of mutual fund expenses?
A: We rely on the advisor for that.

There is more, but you get the idea. People like G.K. just don't get it. Her small-minded attitude costs her company money. She is also depriving the employees there of their rights to learn more about their benefits and their rights to better investments. (I will talk about this in the next segment. Stay tuned - it gets MUCH WORSE when we review the investments.)

The bad news is that there are plenty of G.K. s out there. If I were an employee at this company, I'd either want a different person in charge of the 401(k) plan or learn what my legal options are. G.K. is a time-bomb.

You can contact me at http://www.helpmy401k.us/ . Pick up your free report on my website – "The 5 Biggest Problems With 401(k) Plans – And How to Fix Them". My new book, "Help! My 401(k) Has Fallen - And Must Get Up!" is due out in April.

My weekly financial advice program, Improving Your Financial Health is on Blog Talk Radio and Saturday mornings at WHME-FM.      


Wednesday, March 24, 2010

Diary of a Wimpy 401(k) - Editing

Today I spent some time on editing. I had sent out my book to several people and have gotten some good feedback on it.

If you ever write a book, I would absolutely recommend having others take a look and do editing for you. It's almost impossible to do it yourself. I know I probably still missed and have a typo somewhere. Some of the editing also involved changing wording to make it clearer.

One thing that did make me feel a bit better - I was reading "The Christmas Sweater" by Glenn Beck ("Wimpy", I know.) recently and noticed a typo in it. I'm not going to say what or where - you can find it on your own. But its nice to know that others slip up too.

The hardest part was putting together an index. I had done one a few weeks ago and put page numbers on everything. Now with my edits, it changed the page numbers. (As Homer Simpson would say - "D'OH!")
A book like "Help! My 401(k) Has Fallen - And Must Get Up!" definitely needs a good index and also a guide for resources and websites. This book uses several resources for 401(k)s as well as financial authors.

I also had a chance to speak with Pentavision once more. I'm very excited about doing the video for it - even if I can't get Bruce Willis to star. It should be about 30-40 sec and will go up on You Tube when its done. To save on costs, I am trying to locate images myself and send them to be added in.

Also, the domain name is http://www.my401khasfallen.com/ .You can try to go there, but the site isn't ready yet. Once the cover and video are done and also some other details, I'll get it up & running.

In the mean time you can still contact me at http://www.helpmy401k.us/ . Pick up your free report on my website – “The 5 Biggest Problems With 401(k) Plans – And How to Fix Them”.


You may also contact me on Linked In or Twitter . I also host a weekly financial advice program, Improving Your Financial Health on Blog Talk Radio and WHME-FM.

Monday, March 22, 2010

Diary of a Wimpy 401(k) - Movie

Well, my daughter wanted to see the "Wimpy Kid" movie yesterday. I know she likes the book series and they are pretty funny so we went.

The movie was pretty funny, a bit different from the book with several new adventures for the Wimpy Kid, Greg Heffley, as he deals with surviving middle school. You really don't want to know about the "cheese touch".

I'm not planning a "movie" for my book "Help! My 401(k) Has Fallen - And Must Get Up!" Although if Bruce Willis' agent will return my calls, I may change my mind. James Gandolfini might be interesting also......
a 'mafia' financial advisor......hmmmmm.

Seriously, don't look for a movie with either of these guys. Although I am still planning a short video clip with Pentavision. I'm supposed to meet with them again this week.When we put up the new website, the video will be there and we can direct orders to the page on Amazon.

I'm also getting more book cover ideas this week, which I hope to be able to post and get feedback.

My other project is to find blogs on 401(k)s and IRAs and post responses to questions. I have several which I know of.

If any readers want to send me links for 401(k) blogs, please contact me.

You can get a copy of a free report on my website – "The 5 Biggest Problems With 401(k) Plans – And How to Fix Them".


You may also contact me on Linked In or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health on Blog Talk Radio and WHME-FM.

Friday, March 19, 2010

Diary of a Wimpy 401(k) - Wimpy Cost Explanation

When I go to buy something – a new pair of shoes, furniture, or dinner at a restaurant – I want to know exactly what I am paying for. You probably do also, unless your name is Bill Gates. Fee clarity is more important than ever.


Since I have been an advisor in South Bend, I’ve gotten to know a lot of people. I’ve been asked on several occasions to join marketing or networking groups. Recently I was invited to join a group which focused on marketing ideas. The ideas seemed good, and I saw some value in joining the group. I thought it may be a great way to plug the upcoming book as well.

However, this week I decided absolutely not to join this marketing group.

Why not ? The group leader did a poor job of explaining all of the costs involved (wimpy?). I went to 3 different meetings, I was bombarded with marketing information, but never once saw cost explained either verbally or in print. When I finally did find out HOW MUCH, it was quite a lot more than what I was originally told. Whatever credibility he had worked to build was gone.

“No B.S.”?…….Yeah, Riiiiiiiiight. One of my first sales managers told me “A confused prospect never buys.”

What does this have to do with 401(k) plans? Simple. One of the biggest problems with plans now is that fees aren’t clearly explained. Employers don’t know costs, and therefore can’t explain them to employees, who are really picking up the bill. Federal law has made it mandatory that all fees for 401(k) plans are clearly itemized and easy to understand.

If a contractor came to my house and told me he would fix my roof for $10,000, and then due to “unforseen expenses” the tab came to $15,000 or more, I’d be upset. You would be too! By the same token, when I review plans for employers, I want to make sure they know all of the fees in the plan. I have also stumbled onto plans which are badly in need of an update. They are still paying for the plan as a ’small’ business, when in fact they could be saving a lot of money once they have reached certain dollar amounts, or breakpoints.

In my book, “Help! My 401(k) Has Fallen – And Must Get Up!” I use an example of cell phones to explain this.

Why would you still pay for a “1980’s backpack style” cell phone, when newer, better, and cheaper models are available?

As an employer, you need to review your 401(k) plan and update it. Don’t be ‘wimpy’. Make sure you know all the costs and your people do too.

You can also get a copy of a free report on my website – “The 5 Biggest Problems With 401(k) Plans – And How to Fix Them”.

You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.

Wednesday, March 17, 2010

Diary of a Wimpy 401(k) - Wimpy Friends

The interesting thing about writing a book - I am learning who my friends are.

One of the things I had wanted was to get testimonials from people from all walks of life. The book was written in simple language with plenty of stories to make it easy for anyone to understand.

We all have a 401(k) or 403(b) - almost all of us anyway. Unless you are self-employed or one of the rare few who still have a pension.  

So about a month ago, I sent requests for testimonials to about 65 people. Some I knew better than others. Some were financial experts who I had interviewed on "Improving Your Financial Health". Some were friends in the financial industry. Some were friends and clients I knew locally, or small business owners. Still others were people who were involved in the project in some way. 

A few were celebs who I didn't know, but I wanted to get a testimonial from them.

In asking for testimonials, I believe that we are all very busy. I am willing to be patient and follow up a few times to get testimonials. These 'blurbs' from others can help to promote the book.

If you have a 401(k) and you aren't happy with it, and you are nervous about the future, you should read this book!

One guy (a writer whom I won't name) turned me down, but was very nice about it. He explained that he gets many similar requests and he simply does not have time to answer them all. He also didn't believe that his testimonial would carry much weight, with him not having a financial background.

Although I was slightly disappointed, I appreciated his sincerity and his prompt response.

I've also had a few of my financial heroes tell me that although they like the book and see its value, they aren't allowed to respond due to compliance constraints. Again, I respect this.

That's one way to do it. Here's the WRONG WAY!

Another previous guest on my program (I won't name her - but I promise she WON'T BE BACK!) had her assistant send this "snooty form letter" remark. "As a policy, our team focuses on content that is being published by a major imprint. We don’t read or consider unsolicited material. Should your book get picked up by a major imprint, please do feel free to reach out to me at that time, and I’ll do my best to get it to (her) for a possible endorsement."


Again, this type of chilly response really alienated me. I've lost a lot of respect for this person and needless to say, she won't be back as a guest on my program.

I am still looking for testimonials. I've gotten several very ones so far. Let me kinow if you'd like a copy of the book for review. If you want to learn more about 401(k)s and think you can write a couple of kind words - contact me and I will gladly send you a copy of the draft.

Here are some of my favorite testimonials so far.

"Unless you plan to work till you drop, the 401(k) is your eventual ticket to freedom. Your plan may have fallen in 2008 and Dean Voelker is just the person to help get it back up." -

Jonathan Chevreau, Financial Post columnist, and author of Findependence Day.

“Dean Voelker does a great job of laying out the case for aggressively pursuing your 401(k). This book presents compelling reasons for getting involved in your future TODAY, rather than tomorrow. Dean’s story telling approach takes the 401(k) from its birth through today in an easy to read and storytelling manner.” - Len Fox, author of Recipe Investing.

“Dean Voelker is a real pro. He reveals some things about the Social Security system and how
401(k)s work that I never knew. This book is short, sweet and to the point. Everyone needs to read it quickly to see if they are doing what they should to get their retirement plans back on track. Thanks, Dean for putting this together for us.” - John S. Cohoat, President of Cohoat Business Growth Advisors, and author of No Thank You, Mr. President.

Go ahead, don't be "wimpy". Contact me today. You can also get a copy of a free report on my website -
"The 5 Biggest Problems With 401(k) Plans - And How to Fix Them"

You may also contact me on Linked In at http://www.linkedin.com/in/dvoelker or Twitter at http://www.twitter.com/deanvoelker. I also host a weekly financial advice program, Improving Your Financial Health at http://www.blogtalkradio.com/401kcoach.


Monday, March 15, 2010

Diary of a Wimpy 401(k) - Getting It Printed

Probably the biggest question to answer was "How are we going to print this thing anyway?"


The LAST thing I want or need is to print up a bunch of books and have them sitting in my garage. I also know that most publishers have never heard of me. So I started getting all kinds of advice from different people. Also did you know that if you sell books to a "brick and mortar" bookstore, they will send you the unsold or damaged books back and are entitled to a full refund including shipping costs? Its in the 'fine print' of the contract.

People suggested e-books, or partial e-books, or different print houses. In January, I interviewed a man named Len Fox, author of Recipe Investing, a book which was not unlike mine, in terms of size and content. Len had used a division of Amazon called Create Space. Len had liked it because it was connected to Amazon. They handled the ordering through Amazon.com and could print 1 book orders. Once a month, they would then pay Len his cut from the book orders. Len didn't have to handle any of it. He got a statement once a month with the orders and a paycheck. No hassle, no damaged books, no refunds, no crates in his garage, no shipping. All of it was done there, by Create Space.

Hmmm - that sounds good to me. I was still working on the writing part at the time, so I kept it on the back burner and also continued to get ideas from others. A few weeks ago, I sent a copy to Carlos Frank, another friend of mine. I had interviewed Carlos twice for my financial show, "Improving Your Financial Health". Carlos suggested that I talk with John Rizzo, who worked for....Create Space.

John Rizzo called me last week and after speaking with him, I was convinced that this was the right path for me.

Create Space offers all types of services that will help you to self-publish your book. Self-Publishing allows you much more freedom and can really lower your cost. John was extremely helpful in explaining all of the services offered. There are 2 things I really like about using Create Space.

First, the services are all seperate. If you need them to typeset or edit or promote your book, they will do it OR if you already have someone that you are using, you can do that. You have the choice. When it comes to assembling the book, all I have to do is send them my material and cover design, and they do it. This is also impressive, since my index and resource guide are seperate from the main manuscript.

Secondly, because of their affiliation with Amazon, they will take care of posting your book on Amazon's site and handle customer ordering and shipping for you. Not only is this a real time and money saver, it also prevents the possiblity of having crates of books taking up space in my garage! I am really looking forward to working with John Rizzo, and I would certainly recommend Create Space if you are looking to get a book printed.

Friday, March 12, 2010

Diary of a Wimpy 401(k) - A Picture Is Worth....

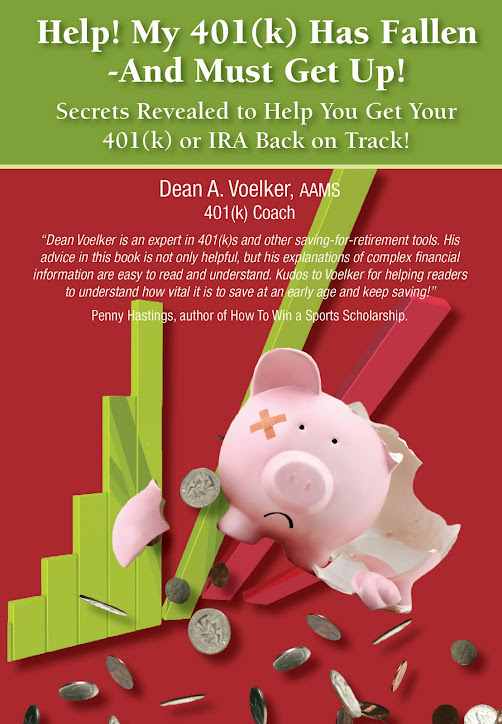
I had a chance to speak with Aimee Sims. Aimee will be working with me on the design of the book cover. You know the saying "Don't judge a book by its cover." Whether we think so or not, that is exactly what we all do.


Aimee was referred to me by my friends at Pentavision, Michael Lacognato and Missy Stanisz. Pentavision may also be helping me with a video idea for the book. More on that to come.

Anyway, since I am using this blog to detail the printing process, here is the first effort. Thanks Aimee for your help on this.

Here are a few other images which we are talking about as well.


If you could, I'd love to get feedback on these potential cover ideas. Good? Bad?
What may cause you to pick up the book in a bookstore?

Thanks for your help and I will keep you posted.