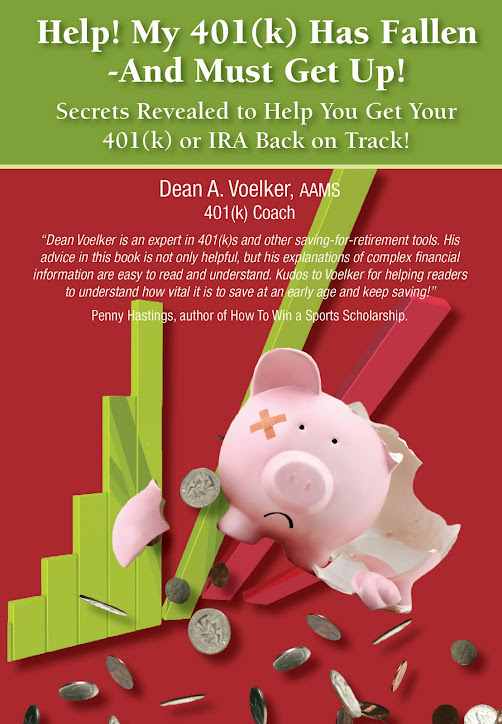
I've been a bit busy this week, working on my upcoming book, "Help! My 401(k) Has Fallen - And Must Get Up!" . This is an "everyman's" (and everywoman's) guide to getting more from your 401(k) plan. Most books I have seen on 401(k) plans really are geared more to advisors and financial people, which is what inspired me to write it.
For most of us, the 401(k) is a major source of our savings, and for some it may be the ONLY source of savings. We need to get more out of it if we want to retire someday and have our money last the rest of our lives. I'm very excited to contribute something unique - and hope others find it helpful.
Anyway, I plan on doing more with the blog and hope that my message finds the right people. Last week I wrote about Blog Talk Radio. My experience with Blog Talk Radio has been great. I began using it in July 2009 on the advice of a friend of mine, Brian Seim, a radio veteran.
Although I have made a TON of mistakes (and still do!), I must have done a few things right also. A few weeks ago I began an affiliation with WHME-FM in South Bend (103.1) . We agreed to replay my interviews from Blog Talk Radio as a 30 minute program on Saturday mornings - "Improving Your Financial Health" .
If I had to pick the one factor which has made the show appealing - its the GUESTS! My guests have mostly been financial experts and authors, although some have been very interesting people with great personalities with no financial background at all. Even so, they had something of value to share with listeners and wer a lot of fun to talk with. Some examples would be Ruben Gonzalez, a 4 time Olympian who has written 3 books on staying motivated, or Charlie Adams, who is also a professional speaker and helps High School athletes to get college scholarships. Kristen Harmel who has written 6 novels and has a passion for helping kids with reading, Kay Yasin who overcame personal tragedies to change her life and is now an expert trainer and bodybuilder, and Darin Pritchett who is well known in the South Bend area for his Weekday Sportsbeat show. These and many others are wonderful people and gave fun & interesting interviews. All would all be welcome guests in the future.
Once I committed myself to doing the program, I have always been on the lookout for people who would make great guests . When I find someone I like, I contact them and and tell them about the program and try to schedule a time for them to be on. Always let them know that you are doing this regularly (for me once a week) and tell them names of other guests I've interviewed.
Whatever you choose to do a program about - for business or for fun - I would certainly recommend having interesting guests that fit in with your message. Again, the guests make the show fun. (Who would want to listen to just me for 30 minutes?)
People have often asked me where I find my guests. You can find guests in several places. My main source would be searching the internet for financial blogs or articles I also subscribe to Money and Smart Money magazines and have found great articles there.
Referrals can be a great source also once you tell others what you are doing. My friend, Nikki Stauffer in Ada, MI deserves a special mention. She has referred 2 nationally recognized financial experts and authors to me who are guests. Eric Tyson (author of "Investing for Dummies" and "Personal Finance for Dummies") was one. There aren't many financial advisors out there who can say they have their own "jingle" written by Paul Shaffer of the David Letterman band. Another is Robert Krakower, who has graciously agreed to be interviewed on March 23. His new book is titled "Redefining Retirement for a New Generation".
By the way, Nikki Stauffer has a great weekly show of her own, "Gather Round the Table" . She has also done pretty well with guests, including Megyn Price (Rules of Engagement), Maria Canals-Barrera (Wizards of Waverly Place), and Mayim Bialik (Blossom), among others. This program promotes the importance of family values by eating meals together, and Nikki's guests normally share one of their favorite recipes. Check out her site and archived interviews at http://www.gatherroundthetable.com/.
I also need to thank Erica Sandberg one of my early guests, and author of "Expecting Money", for her referral of a colleague of hers, Sally Herigstad, CPA, and author of "Help! I Can't Pay My Bills!". Both ladies were wonderful guests and I look to have them on Blog Talk Radio again.
Pam Batcho of Express Pros, also has been a great referral source. She referred Ruben Gonzalez, whom I mentioned earlier and also her boss, Norm Robertson, owner of the local Express Pros branch.
Sometimes, it pays to be persistant. Anya Kamenetz was a young lady I had really admired from reading her first book, "Generation Debt" a few years ago. It highlights the challenges of being young today, especially with the high costs of college and student loans. Anya was nominated for a Pulitzer Prize for her efforts.
She is also a nationally recognized speaker, and has appeared on college campuses nationwide.
I knew Anya would make a great guest, and tried to e-mail her (4 times over 6 weeks) with no reply. Finally one day out of the blue, I got a very kind note from her. She apologized that she had been out of town and wasn't getting her e-mails. She also sent me her personal e-mail and agreed to an interview. The interview went great and it was quite an honor for me.
Whoever the guest is, I really try to be respectful of their time. I really want to make sure the experience goes well for them - I may want to have them back sometime, or want their help with a project.
Before doing a program, I send the guest specific instructions confirming the date and time and Call-In phone number. Since some of my guests live in different parts of the country, I also make sure I note EST - and whatever time it may be for them. 1:00 pm here is 10:00 am in California. That may seem like a small thing, but trust me - its important!
Another habit of mine is to send the guest a list of questions personally tailored to them. Some guests have even suggested questions that the like to be asked. By reviewing their website or reading their books, it has helped me quite a bit to learn about them. It helps the interview to go more smoothly.
My objective is to build them up as an expert which (I hope) makes me look like a good guy as well. Speaking of building up, its also very important to use a proper introduction. A good introduction should be at least 3 sentences, highlighting their achievements. You are telling your listeners why you chose this person to be on your show and why their advice will be valuable to them.
One last point on guests - You can't say "Thank You" enough. I always thank them at the end of the program and give them a chance to give contact information and promote their book or services . After the show, I also send an e-mail thanking them for their time once more.
Blog Talk Radio has been a great venue for me. I plan on writing one more article about Blog Talk Radio, which includes tips and techniques. You can contact me through my website, http://www.helpmy401k.us/ and
through Linked In or Twitter.
There is a Free Report now available through my website, "The 5 Biggest Problems With 401(k)s - And How To Fix Them". Please contact me to receive your free copy. This is a sample of my upcoming book, "Help! My 401(k) Has Fallen - And Must Get Up!"
Showing posts with label Wall St Journal. Show all posts
Showing posts with label Wall St Journal. Show all posts
Sunday, February 21, 2010


Friday, October 23, 2009
Wipe Out The Fear in South Bend

Feel like you are drowning in today's economy?
Inflation?
Shaky stock market?
Sinking dollar?
Unemployment?
Staggering debt?
Inflation?
Shaky stock market?
Sinking dollar?
Unemployment?
Staggering debt?
Watching the news may seem like an ongoing care wreck - especially if you watch Glenn Beck, who always looks like he will suffer a breakdown right on camera - but as horrifying and overwhelming as the news is, you can't seem to pull yourself away.
We don't suffer from a lack of information - rather TOO MUCH information. Its all so confusing and you can feel like the rag doll being pulled apart from all directions.
How does all of this affect your ability to save for retirement? Is it possible to still have goals and dreams? Can you still retire with dignity?
Dan Rather was once quoted as saying "If all of the difficulties were known at the outset of a long journey, most of us would not start out at all."
Nothing great was ever achieved without hardships along the way. As an advisor, my job is to help you resolve your fears. Let's wipe them out and provide some peace of mind.
This year, when I became an iindependent advisor and opened my own office, I've been learning that most people would rather "not lose anymore" than to win with their long term savings. To quote another great American, Will Rogers - "I'm more concerned with the return OF my money than the return ON my money."
With that in mind, my purpose has been to focus on helping people to find a vehicle that would "not lose" and still let you win. What if I could toss you a "Life Preserver" for your savings? Remember when you first learned to swim? Those kickboards or noodles came in handy, didn't they? You learned eventually that the water is your friend. Once you stopped fighting it, and let it help you, swimming became more fun, right?
Russell Pearlman recently wrote an article titled, "Problems? What Problems?" from the November 2009 issue of "Smart Money" magazine. His article focused on annuities, which have become much more popular with investors as a life preserver for long term savings.
"Don't tell that (regarding annuity cost) to baby boomers looking for retirement security at a time when their 401(k) plans are still hurting; they just keep buying annuities. Through the first six months of the year, total annuity sales were almost $127 billion, only a 3 percent drop from 2008." he writes.
Again, the message I get from my clients and others I meet is "We want SAFETY and Peace of Mind."
Can we get "Guaranteed" growth for our long term savings?
Will it be better than current CD rates?
Can we get "Guaranteed" income when I retire - also better than current CD rates?
Can we make sure the income never goes down?
And lasts for a lifetime - even if we live to 100 or beyond?
And when that lifetime does end, can we leave something for our family and loved ones?
In short - YES! Mr. Pearlman goes on to write "Are annuities for you? Experts say the peace of mind may be worth it."
Another of my favorite articles this year was written by Leslie Scism of the Wall Street Journal. "Long Derided, This Investment Now Looks Wise". "Because of such guarantees, many holders of variable annuities actually saw their accounts increase 6% or more in value last year, when the Standard & Poors 500 stock index dropped nearly 39%." Ms. Scism writes.
Contact me today to learn more about how to get a life preserver (or noodle if you prefer) for your savings. Treat yourself to some Peace of Mind!
You can contact me through my website, http://www.helpmy401k.us and follow me on Twitter at http://www.twitter.com/deanvoelker. I also host a weekly internet radio braodcast, "Improving Your Financial Health" at http://www.blogtalkradio.com/401kcoach.
Tuesday, August 18, 2009
If You Knew You'd Get a "B"

Soon, all the kids will be back in school. My daughter can’t wait to see her friends and show off her new outfits. Back-To-School time usually also means plenty of sales which should get the cash registers ringing in your local retail shops.
Since we are just getting started, it’s too early to think about report cards and grades yet….or is it?
What if you knew at the beginning of the year, that your grade at the end of the year would be at least a “B” and no worse – no matter what? Better still, what if you got an “A” in one quarter, and a “C” in the other quarters – and at the end of the year, you got to keep the “A” as your grade for the year?
If that were true, how would you feel about going to school? Would you be more relaxed? Would you want to learn more? Would school be more fun?
Well, GUESS WHAT!! I can’t do much about Johnny’s math grade, or Susie’s US History Course, but I can provide solutions which may improve your confidence in investing.
How can you do that, you ask? Variable Annuities can provide Safe Growth and Safe Income.
How can you do that, you ask? Variable Annuities can provide Safe Growth and Safe Income.
Recently, Leslie Scism of the Wall Street Journal wrote “Because of such guarantees, many holders of variable annuities actually saw their accounts increase 6% or more in value last year, when the Standard & Poor’s 500-stock index dropped nearly 39%.” in her article “Long Derided, This Investment Now Looks Wise”. http://online.wsj.com/article/SB10001424052970204900904574302270919454880.html
Currently, you can earn as much as 7% or more on your principal base when you aren’t using it for income. That means if you start with $100,000, by the end of the year, you would have $107,000 to draw income from later – no matter what happens in the market. (As long as you leave it there.) And it can grow tax-deferred until you begin to take it out.
What if your account does better than 7%? Also, what if it only does better than 7% for one quarter? Wouldn’t it be great to keep the best quarter and lock it in for the year? Well….you CAN!
What if you could do this every year while you are building your Nest Egg? What if you went into the school year knowing you would at least get a “B”….and might get an “A”?
Then when you begin to take income from your savings, you can take 5% from the nest egg you’ve built for the rest of your life. The check would go up or stay the same, but never go down. (As long as you aren’t taking more than 5%.) Would that be OK?
There are some drawbacks to a Variable Annuity, which Ms. Scism also points out in her article http://online.wsj.com/article/SB10001424052970204900904574302270919454880.html the most obvious being the cost of the extra protection. George Lambert also points this out in his article, “The Cost of Variable Annuities” http://www.investopedia.com/articles/pf/06/variableannuity.asp in which he looks at the different types of protection – Growth Protection, Income Protection, and Death Benefit.
Another drawback is that when you consider investing into a Variable Annuity, you need to take a Long Term approach – like any other investment. Speak with a reliable advisor about whether or not it may be appropriate for you based on your time horizon and income needs at retirement. Early withdrawals may result in steep surrender charges, although many plans allow you to withdraw as much as 10% with no surrender charge.
The main advantage of course is taking the uncertainty over today’s economy out of the picture. And if you knew you’d get at least a “B”, wouldn’t you sleep better at night?
For more information on annuities, or other investment ideas, you may contact me at http://www.helpmy401k.us/. You may also follow me on Twitter at www.twitter.com/deanvoelker. I am also hosting a weekly internet radio podcast at http://www.blogtalkradio.com/401kcoach.
Thursday, July 23, 2009
This Time Its Different - II
Recently I posted an article, titled “This Time It’s Different”. Most people when asked about the idea of investing in the market, have responded that “They are waiting to see what happens” and yes, “This Time It’s Different because…..”
If you read my previous article, “This Time It’s Different”, http://5reasonsyoushouldownaroth.blogspot.com/2009/07/this-time-its-different.html I referred to a study done by Hartford on the Recession of the mid 1970’s (1973 & 1974), arguably the closest parallel to our present economic situation. The low point in the market was Sept. 30, 1974. The Dow closed at 607.87 (not a misprint) This was down more than 40% from its high in 1972, when it crossed the 1000 mark for the first time. http://www.democraticunderground.com/discuss/duboard.php?az=view_all&address=389×4124348
The stock market had gone through back-to-back negative years for the first time since the Great Depression.
We should set the stage a bit at this point. In 1972, we were still heavily involved in the Vietnam War, which was highly unpopular, and dragged on for several years. Also, in 1972, the Watergate scandal began. This resulted in the indictment and conviction of several of Nixon’s closest advisors, and ultimately in the resignation of the President himself, on August 9, 1974. http://en.wikipedia.org/wiki/Watergate_scandal
To make matters worse, the Oil Embargo http://en.wikipedia.org/wiki/1973_oil_crisis was put into effect by OPEC, which refused to ship oil to the US due to their support of Israel at that time. Unemployment had reached a high of 6.7% in 1974. http://www.nytimes.com/2008/12/06/business/economy/06jobs.html
So things in 1974 looked pretty bleak. I recently read a letter written by Jim Fullerton of the Capital Group to shareholders at that time(November 1974). Here are some highlights from Mr. Fullerton’s letter.
“Each economic, market, and financial crisis is different from previous ones. But in their very difference, there is commonality….. Today there are thoughtful, experienced, respected, economists, bankers, investors, and businessmen who can (tell) you why this time the economic problems are different; why this time things are going to get even worse – and hence, why this is NOT a good time to invest in common stocks, even though they may appear low…..This time is a whole new ball game.”
“In 1942 everybody knew it was a whole new ball game…..The Germans had overrun France. The British had been thrown out of Dunkirk. The Pacific Fleet had been disastrously crippled at Pearl Harbor. We had surrendered Bataan, and the British had surrendered Singapore. The U.S. was so ill-prepared for a war that……75% of our field artillery was equipped with horse-drawn, French 75mm guns.” (Mr. Fullerton served in WWII.)
“In April 1942, inflation was rampant…..On April 8, 1942, the lead article in the (Wall Street) Journal was: ‘Home Construction, Total far behind last year’s. Private Builders hardest hit.’…..Washington D.C. also considered more drastic rationing with price fixing, or still higher taxes as a means of filling the ‘inflationary gap’ between increased public buying power and the diminishing supply of consumer goods.”
“A leading stock market commentator wrote: ‘The market remains in the dark as to just what it has to discount. And as yet, the signs are still lacking that the market has reached permanently solid ground for a sustained reversal.”
“Yet on April 28, 1942, in that gloomy environment, in the midst of a war we were losing, faced with excess-profits taxes and wage and price controls, shortages of gasoline and rubber…..and with the virtual certainty…..that once the war was over, we’d face a post-war depression, the market turned around.”
“Now I’d like to close with this: ‘Some people say they want to wait for a clearer view of the future. But when the future is again clear, the present bargains will have vanished. In fact, does anyone think that today’s prices will prevail once full confidence has been restored?’ That comment was made by Dean Witter in May of 1932 – only a few weeks before the end of the worst bear market in history.”
“Have Courage! We have been here before – and we’ve survived and prospered.”
Jim Fullerton
As of today, July 23, 2009, the Dow is up nearly 200 points, crossing the 9000 mark for the first time this year. This is a gain of over 38% from its low point of 6547 on March 9, 2009. Yes, This Time It’s Different.
For more information, you may contact me at http://www.helpmy401k.us. You may also follow me on Twitter at www.twitter.com/deanvoelker.
Saturday, May 2, 2009
Am I Getting The Most From My 401(k)?
Today's economic conditions seem to create more questions than answers.
Yet the fact remains - we need to continue to save (and invest) in order to retire with dignity.
Dave Kansas makes a good point in a recent article "What Do I Do Now?" (Wall Street Journal - April 10, 2009) http://www.marketwatch.com/News/Story/do-do-now/story.aspx?guid=%7BE341FAB9-B0EC-4310-8E19-E03CE63FB7E4%7D when he quotes the author, Rudyard Kipling. "Keep your head about you as everyone is losing theirs."
That is what many good advisors tell you, although it is easy to say....and hard to do.
Another problem is that company retirement plans have become increasingly complex. Features such as online investing and elections, and mulitiple fund choices were designed for convenience, but actually may cause people to become "accidental " investors, which leads to confusion and inconsistent results.
This can present a problem for businesses who have a Fiduciary Responsibility to their employees to provide the highest quality investments and proper education on how to invest, why to invest, and how much to invest - at a reasonable cost.
Alliance Bernstein did a study recently http://www.deanvoelker.com/files/ab401kreview.pdf.
They found that both plan sponsors and participants want to "keep it simple".
(Hmmm....imagine that!)
Plan sponsors must review their plans on a regular basis. They need to make sure they are working with a professional who can meet with employees regularly and "keep it simple."
A strategy must be put in place to make sure you are saving enough.
http://www.helpmy401k.us/investment-tools.htm Please use the 401(k) calculator to see if you are on track for your goals.
Employees should also ask their plan sponsor about how funds are selected. There needs to be enough selection to be diversified, but not so much that it is overwhelming.
"Keep your head about you while everyone else is losing theirs." (Kipling)
"Be fearful when others are greedy, and greedy when others are fearful." (Buffett)
Please contact me at www.deanvoelker.com for more information.
Subscribe to:
Posts (Atom)